Assumable Mortgages in Utah: Key Insights for Investors
Assumable Mortgages in Utah: Low Rates, Hidden Holding Costs, and What Investors Must Check
An assumable mortgage can unlock below‑market mortgage rates in today’s Utah real estate market, but delays and holding costs can quietly erase that advantage if you’re not prepared.
Why Assumable Mortgages Look So Attractive in Utah Right Now
With 30‑year fixed mortgage rates in Utah hovering roughly between 7.1% and 7.5% as of early October 2026 (and some lenders posting as high as 7.875% according to Experian, Realtor.com, SmartAsset, and Zillow), any chance to step into a lower rate is compelling for real estate investors and the agencies that serve them.
That’s exactly the appeal of an Assumable Mortgage: instead of originating new debt at today’s higher mortgage rates, a buyer can assume the seller’s existing loan and keep the original interest rate and remaining term. On Utah investment properties, this can mean inheriting a 3–4% rate from a loan written years ago, dramatically improving projected cash flow or flip margins on paper.
📌 Key Takeaway: In a 7%+ rate environment, a sub‑4% assumable mortgage can look like free money but only if the deal actually closes on time and the numbers support the extra equity needed.
The Tradeoff: Low Rate vs. Rising Holding Costs During Delays
Assumptions rarely move as quickly as standard purchases. Lenders must review the new borrower, underwrite the file, and process additional documentation. In Utah, you may also be working through a state Assumption Addendum to the Real Estate Purchase Contract, which adds more steps and signatures.
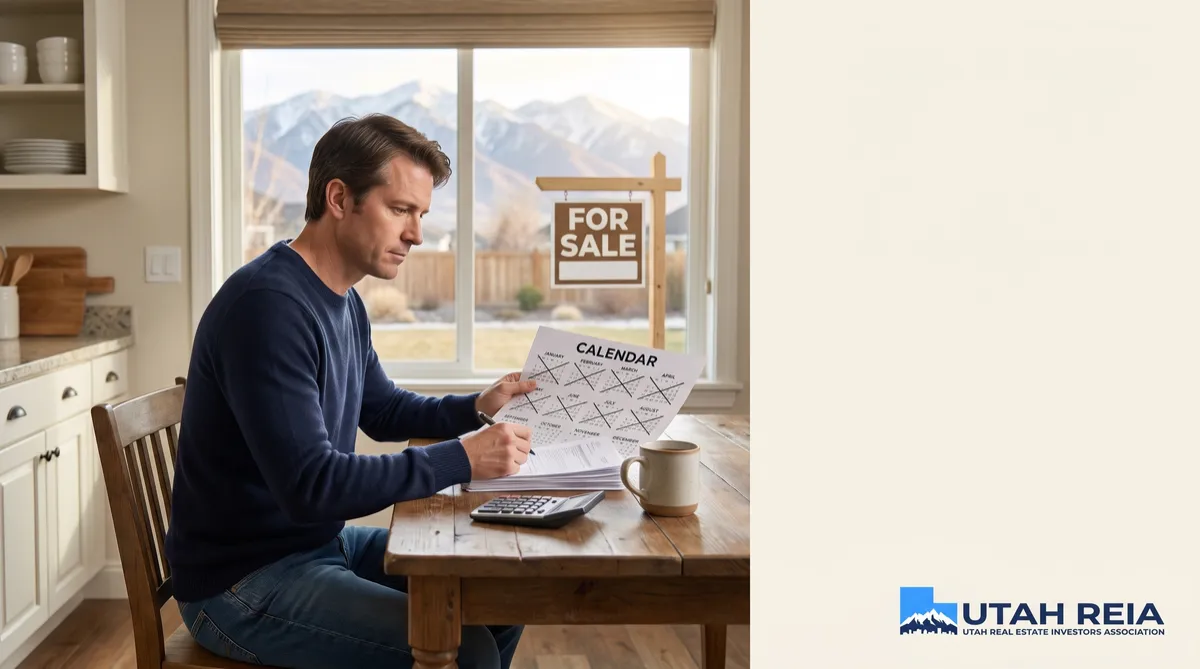
Every extra week in that process increases your holding costs. While you’re waiting for approval:
You’re paying interest (on bridge or hard‑money financing if you used it to secure the deal).
Property taxes about 0.57% annually in Utah continue to accrue.
Insurance, utilities, HOA dues, and maintenance reserves still hit your pro forma.
On a $400,000 Utah rental, it’s common to see total monthly holding costs in the $2,300–$2,600+ range when you include mortgage payments, taxes, insurance, and maintenance reserves. Stretch an assumable‑mortgage closing an extra 45–60 days, and you may burn through $3,000–$5,000 in additional carrying costs wiping out much of the savings from that attractive rate.
Extra 60 days of carrying costs can quickly erode low-rate mortgage savings.
What Utah Investors Should Check Before Building a Deal Around an Assumable Mortgage
For Utah real estate investors, agencies, and investment groups, the key is to underwrite the process risk as carefully as the property itself. Before you center your deal around an assumable mortgage, confirm the following:
Is the loan truly assumable? FHA and VA loans are generally assumable under federal rules, while many conventional loans include due‑on‑sale clauses that block assumptions without lender consent. For Utah Housing Corporation loans, program‑specific rules, income limits, and fees may apply review them early.
Exact mortgage terms and remaining balance. Get a written payoff statement and confirm the current interest rate, remaining term, and payment. Compare that to current Utah mortgage rates so you can quantify the real monthly savings.
Equity gap and required cash. If the property is worth $500,000 and the assumable balance is $320,000, you’ll need to cover the $180,000 gap with cash or secondary financing. Layering a high‑interest second lien can undermine the benefit of the low first‑position rate.
Timeline and lender capacity. Ask the servicer how long assumption approvals are taking in practice 30 days, 60 days, longer? Build that into your Utah real estate contract deadlines and your holding‑cost budget.
Fees and remaining liability. Some programs cap assumption fees; others allow the lender to charge more. Clarify whether the seller is released from liability and who pays what at closing, especially if you’re structuring deals for investors as a brokerage or acquisitions agency.
Turning Assumable Mortgages into a Reliable Strategy
In Utah’s competitive investment property market, an assumable mortgage can be a powerful tool for real estate investors, especially buy‑and‑hold owners focused on long‑term cash flow. But the winning deals come from teams that:
Verify assumability and loan terms upfront.
Budget conservatively for holding costs and potential delays.
Align contracts, timelines, and financing structures with the lender’s actual process, not best‑case assumptions.
When you treat low‑rate assumptions as one input in a disciplined underwriting model—not the entire thesis of the deal you can help your clients or your own portfolio capture the upside of favorable mortgage rates while keeping holding costs firmly under control.